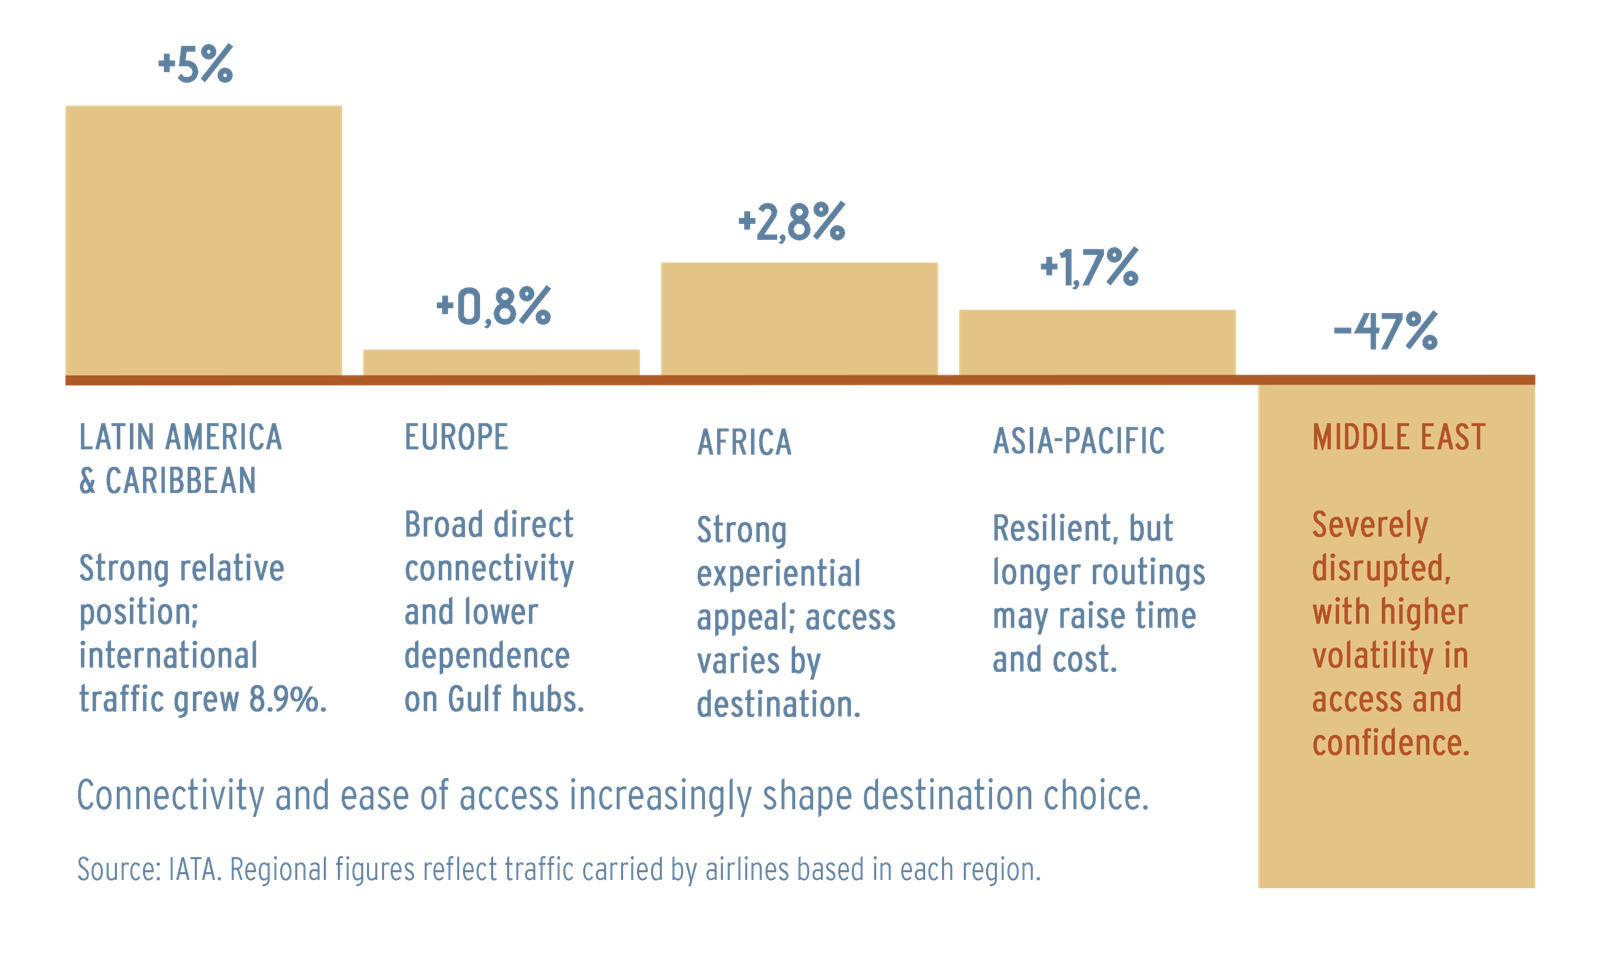
Demand is broadening toward destinations offering stronger value and a clearer sense of safety.
VALUE NOW INCLUDES THE ENTIRE JOURNEY
Luxury value is no longer defined only by the hotel, itinerary or room rate.
CAN I GET THERE EASILY?
• Clear routes, reliable connections and realistic transfer times.
IS THE TOTAL EXPERIENCE WORTH IT?
•Clients evaluate the flight, airport, arrivals, crowds, weather and ease of moving around.
CAN I UNDERSTAND THE PRICE?
• Transparent pricing matters more as clients question inflated or heavily bundled rates.
WILL SOMEONE HELP?
• Fast answers, practical alternatives and a person who takes responsibility.
A strong hotel can still lose the booking if the overall journey feels opaque or too complicated to enjoy.
WHAT HOTELS AND DMCs NEED TO DO NOW
Turn uncertainty into something the advisor can manage.
01
MAKE ACCESS CLEAR
Explain the best gateways, likely pressure points and realistic alternatives.
02
BUILD FLEXIBILITY INTO THE SALE
Use short holds, credits and postponement options to help hesitant clients commit.
03
PREPARE THE ALTERNATIVE
Identify backup airports, routings and itinerary options before disruption happens.
04
MAKE PRICING EASY TO UNDERSTAND
Show what is included and avoid opaque, heavily bundled rates.
A strong hotel can still lose the booking if the overall journey feels opaque or too complicated to enjoy.
TL PORTFOLIO IN LATIN AMERICA
THE CRUCIAL VALUE OF LOCAL SUPPORT
When plans change, clients and advisors need someone on the ground who can act.
01
RELIABLE PERSONAL RELATIONSHIPS
• Real relationships between in country providers and advisors are more significant than ever.
02
A DMC THAT SOLVES
• Real relationships between in country providers and advisors are more significant than ever.
03
INFORMATION THE ADVISOR CAN USE
• Current access updates, clear terms and practical recommendations — not generic reassurance.
04
SUPPORT BEYOND THE HOTEL
• The trip now includes the airport, transfers, local movement and the response when conditions change.
In uncertain times, RELIABLE LOCAL SUPPORT IS ESSENTIAL.
THE NEW COMPETITIVE ADVANTAGE
1. EASY TO REACH
Clear access and credible alternatives.
2. EASY TO BOOK
Simple terms, transparent pricing and faster decisions.
3. EASY TO CHANGE
Strong local support when plans change, favorable terms and conditions
4. EASY TO TRUST
Build personal relationships.
Demand is still there. Confidence helps decide where it goes. In a disrupted world, the most valuable luxury may be peace of mind.
TL PORTFOLIO IN LATIN AMERICA
This report is based on Insights from:
1. IATA
Passenger demand, regional performance, bookings, capacity and Q1 destination growth.
2. U.S. NTTO / APIS I-92
Bilateral passenger traffic between the U.S. and key country markets.
3. UN Tourism & national bodies
Middle East arrivals and country-level tourism performance.
4. Airport and airline reporting
Dubai, Heathrow, Changi/Singapore and alternative-hub traffic shifts.
5. Embark Beyond Q1 & Q2 2026
Frontline luxury booking, pricing, destination and hub-use trends.
6. Reuters and industry reporting
Airline suspensions, rerouting, booking shifts and destination substitution.
7. Methodology note
IATA destination data covers North American origin traffic. NTTO counts total bilateral passenger movements. Momentum markets are directional, not directly comparable.
Please, fill out the details below and we will get back to you:
Register:
If you want to reveice our newsletters, please, fill out the details below
Get in contact:
Please, fill out the details below and we will get back to you, or send an email to info@tl.world
Please sign up to access THE BRIEF – LUXURY TRAVEL IN A WORLD OF DISRUPTION
[ The Brief ]
The brainy side of TL – now officially dubbed TL Mind – had a lightbulb moment: what if we sifted through industry reports, pulled out the essentials, and turned them into bite-sized insights you can actually use day to day?
Meet: The Brief “LUXURY TRAVEL IN A WORLD OF DISRUPTION” Trends made simple. Insights made useful.